

FloatMe: Fast Cash Advance App

- 20.20K Reviews
- 4.5
- Downloads
- 1,000,000+
Our take on FloatMe: Fast Cash Advance App from Appgk
When an unexpected expense lands a few days before payday, the problem is often not long-term debt but a short, awkward gap in timing. FloatMe: Fast Cash Advance App is built around that exact situation. I reviewed it as a finance app from FloatMe, and my overall impression is that it can be a practical emergency bridge for eligible users who need a small amount quickly, while being a poor substitute for a proper budget, savings cushion, or lower-cost borrowing option.
The central appeal is easy to understand: the app focuses on cash advances without interest or a traditional credit check. That makes it feel more approachable than a credit card application or a conventional personal-loan process. Still, “easy to access” should not be confused with “free money.” The advance has to fit into the user’s next pay cycle, and that repayment timing is the detail I would think about most carefully before using it.
How FloatMe fits into a real payday emergency
In everyday use, the most sensible way to view FloatMe is as a short-term timing tool. Imagine that a utility bill is due on Friday, your paycheck arrives on Monday, and postponing the payment would create a late fee. An app centered on a cash advance may solve that immediate mismatch more directly than applying for a credit card. The benefit is not that it changes your income; it gives you another way to manage the few days between an obligation and your regular pay.
That distinction matters because the app is not designed to replace ordinary banking. I would not open it expecting a full checking account, a detailed investment platform, or a long-term debt-management system. Its purpose is narrower, and that narrow purpose is also its strongest point. When the need is genuinely temporary, a focused tool can be easier to understand than a large financial product packed with features you do not need.
Best Parts of FloatMe: Fast Cash Advance App
Things to Keep in Mind About FloatMe: Fast Cash Advance App
The app is free to install, and its Everyone content rating makes it broadly approachable from an age-classification perspective. It runs on Android devices using version seven or later, so compatibility should be reasonable for many older phones as well as newer ones. FloatMe has been available since October 2018, which gives it a longer presence than a brand-new emergency-finance app. The current release is version 8.21.0, so I would still keep the application updated before relying on it for a time-sensitive request.
Its public reception also suggests that many people have found the concept useful. FloatMe holds a 4.5 average from roughly seventy-eight thousand ratings, with about twenty thousand written reviews and more than a million installs. I treat those figures as context rather than a guarantee: a high average cannot tell me whether a particular person will qualify, how quickly an individual request will be handled, or whether the repayment schedule will suit that person’s income.
News and Features Related to FloatMe: Fast Cash Advance App

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The strongest part is the simple emergency use case
The clearest strength is the way FloatMe addresses a familiar financial problem without making the user begin with a conventional credit application. If your issue is a short cash-flow interruption, avoiding interest and a credit check can be meaningful. Someone with limited credit history may find this more approachable than a bank product, while someone who normally manages money well may appreciate having a backup for an isolated surprise.
I also like the psychological clarity of separating an advance from a larger loan. A traditional loan can encourage people to think in monthly payments and extended borrowing. A cash advance forces a more immediate question: can I cover this amount when my next paycheck arrives? That shorter horizon can help a careful user keep the decision tied to a specific bill rather than turning it into general spending money.
Don't want to read the full review?
There is a useful workflow hidden in that idea. Before requesting anything, I would write down the exact expense, the date it must be paid, the date income is expected, and the amount that will remain after normal essentials. Only then would I decide whether an advance is sensible. This small preparation step prevents a common mistake: using a short-term product for a recurring shortfall that will still exist after repayment.
Another practical habit is to treat the app as a last-mile solution rather than the first stop. I would first check whether the biller offers a grace period, whether a payment date can be moved, or whether an existing bank balance can cover the expense without creating a new obligation. If those choices are unavailable or more expensive, FloatMe becomes easier to evaluate on its own terms.
Screenshots
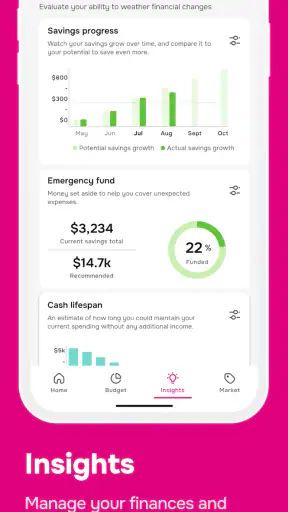
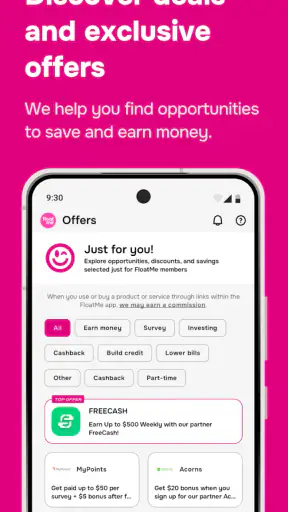
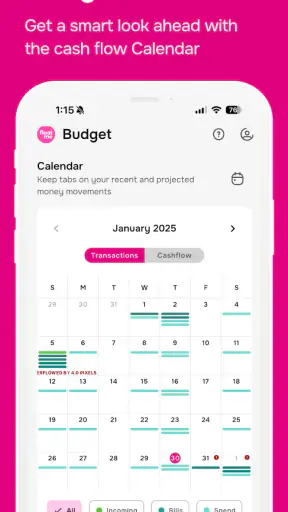
What the no-interest promise does and does not solve
The absence of interest is a major reason someone might consider the app, but it does not remove every cost or every risk associated with short-term borrowing. Users should read the in-app terms carefully, including any optional service, expedited delivery, eligibility condition, or repayment detail shown during the request. I would never assume that a headline benefit describes every possible path through the app.
The lack of a traditional credit check can also be viewed in two ways. It may make access less intimidating, but it does not mean approval is automatic. Financial apps commonly evaluate whether a request fits their requirements, and the user should be prepared for the possibility that the available amount or timing will not match the emergency. In other words, I would not wait until the final hour to discover whether the app can help with a bill due that same day.
That is one of my most important practical recommendations: install and understand the process before an emergency occurs. Review the screens, confirm that the device is compatible, and learn where the repayment information appears. A calm trial of the interface is far better than trying to interpret unfamiliar instructions while a late fee is approaching.
The meaningful weakness is the repayment squeeze
FloatMe’s biggest limitation is not the idea of a cash advance; it is the possibility that repayment makes the next payday even tighter. If the advance covers groceries today but leaves too little for rent, transportation, or another automatic bill later, the app has only moved the pressure forward. That can create a cycle in which each paycheck is partly committed before it arrives.
I would therefore skip FloatMe when the same shortage happens every pay period. Recurring expenses need a structural answer, such as reducing a bill, changing the payment date, increasing income, or speaking with a nonprofit financial counselor. A short-term advance may be appropriate for a one-off repair or urgent purchase, but it is a weak solution for an ongoing gap between income and essential spending.
There is also a timing risk. A user may think, “I only need this until payday,” but payroll timing, bank processing, weekends, or an unexpected deduction can change the amount available when repayment is due. I would leave room for those possibilities instead of budgeting every last dollar. If repayment would require skipping an essential bill, the advance is not affordable, even if the original expense feels urgent.
This is where FloatMe compares differently with the usual alternatives. A credit card can offer more flexibility, but interest may make a carried balance expensive. A bank overdraft may be convenient, yet its fees and policies can be difficult to predict. A personal loan can provide a larger amount and a longer schedule, but it is excessive for a small, short-lived gap. Borrowing from a trusted person may cost less financially, though it can create personal tension. FloatMe sits between these choices: more targeted than a loan, potentially less costly than interest-bearing credit, but still dependent on disciplined repayment.
Who will get the most value from it
I see the best fit as someone with regular income, a clearly identifiable one-time expense, and enough certainty about the next pay cycle to repay without sacrificing essentials. For that person, the app can function as a controlled emergency valve. The user should already know why the money is needed and exactly where the repayment will come from.
It may also suit someone who would otherwise resort to a high-cost short-term lender. In that comparison, an advance with no interest can be an appealing alternative, provided the user understands all terms shown in the app and does not treat the available amount as extra income. The value is strongest when it prevents a more expensive decision, not when it encourages additional discretionary spending.
I would be more cautious recommending it to a person with irregular income, multiple overdue bills, or no realistic repayment plan. Someone already juggling several advances or relying on borrowed money for food and housing needs broader support than a single finance app can provide. Likewise, users looking for credit-building should not assume that a cash advance serves the same purpose as a conventional credit product; the two solve different problems.
People who prefer comprehensive money management may also find FloatMe too focused. A budgeting app can help identify recurring leaks, while a bank account may offer a clearer view of income and bills in one place. If the real issue is not timing but overspending, FloatMe treats the symptom rather than the cause. I would choose a budgeting workflow first in that situation and use an advance only if a separate, temporary emergency remained.
Small decisions that make the experience safer
My first tip is to name the expense before opening the request flow. “Emergency” is too vague. “Prescription due Wednesday” or “car repair needed for work” gives the decision a boundary. If you cannot state the purpose clearly, that is a sign to pause rather than borrow automatically.
Second, compare the repayment date with every fixed payment that follows it. The relevant question is not simply whether your next paycheck is larger than the advance. It is whether the paycheck remains sufficient after rent, utilities, transport, food, subscriptions, and any automatic withdrawals. This is a more useful test than focusing on the amount offered on screen.
Third, keep records of what you accept and when it is due. I would save the confirmation details and check the repayment information again after the transaction, especially if the request was made during a stressful situation. A simple calendar reminder can help prevent the advance from disappearing from your attention until the due date arrives.
Finally, do not let the absence of a credit check become a reason to stop comparing options. Ask whether a bill extension, employer advance, community resource, or existing emergency fund would leave you in a better position. FloatMe is most useful when it is one considered option among several, not an automatic response to every shortfall.
My verdict after weighing convenience against control
After looking at the app as a real financial tool rather than a quick fix, I think FloatMe earns consideration for a narrow but important job. Its free availability, focus on cash advances, and promise of no interest or credit checks make it more approachable than many conventional borrowing routes. The large install base and strong average rating add confidence that the concept is useful to a substantial audience, although neither replaces careful reading of the terms.
My recommendation is simple: use FloatMe only when the expense is temporary and repayment is already mapped out. In that situation, it can help bridge a payday gap without forcing you into a larger product than you need. I would not recommend it as a recurring income supplement, a budgeting strategy, or a way to make nonessential purchases feel affordable.
For a disciplined user facing one unexpected bill, FloatMe is a focused and potentially helpful finance app. For someone whose financial pressure repeats every pay cycle, a budget review, creditor conversation, or longer-term support will be more valuable. That distinction is the key to getting something useful from FloatMe without allowing a convenient advance to become another source of financial stress.
FloatMe: Fast Cash Advance App FAQ
What is FloatMe: Fast Cash Advance App, and how does it work?
FloatMe is a financial app that may help eligible users access a small cash advance before their next payday. After creating an account, you generally connect a qualifying bank account, review the available advance amount, and choose whether to request it. The money is then delivered according to the app’s stated transfer options and timing. Availability depends on eligibility, account history, and other requirements.
How much money can I borrow with FloatMe?
The amount available through FloatMe is typically a small advance rather than a traditional personal loan. Your limit may vary based on factors such as recurring income, bank-account activity, repayment history, and the information verified by the app. Because limits and eligibility can change, users should check the current offer shown in the app before accepting an advance and avoid borrowing more than they can comfortably repay.
Does FloatMe charge fees, membership costs, or interest?
FloatMe’s pricing may include a subscription or membership fee, along with possible charges for optional features or expedited delivery, depending on the plan and terms presented to you. Cash-advance products may work differently from conventional loans, so users should carefully review the total cost, renewal terms, transfer fees, and any applicable disclosures before proceeding. Never assume that an advance is free simply because it does not use traditional interest.
How quickly does FloatMe send the money, and when must it be repaid?
Delivery speed depends on the transfer method you select, your bank, verification status, and whether you qualify for an expedited option. Standard transfers may take longer than instant delivery, and additional fees may apply for faster access. Repayment is generally scheduled around your next expected income deposit, but the exact date and amount should be confirmed in the app so you can maintain enough funds in your account.
Is FloatMe safe to use, and what information does it require?
FloatMe may request personal and financial information, including identity details and access to a connected bank account, to verify eligibility and evaluate repayment ability. Before signing up, review the app’s privacy policy, security practices, permissions, and customer-support options. Download it only from an official app store, use a secure password, and avoid sharing login credentials. Financial apps can reduce short-term stress, but users should also understand the privacy and repayment risks.











